Insurance
-
Comprehensive Motor, Project and Critical Illness in Malaysia
Three insurance policies that are easy to mix up
Malaysian households and small firms often hold several insurance contracts at once and then treat them as if they were variations of the same product. They are not. A comprehensive motor policy, a contractors’ all risks policy, and a critical illness plan each pay for a different kind of loss, on different terms, and at different times. Mixing them up is how people discover a gap only after a claim is declined.
This piece keeps the three apart. It is not a product comparison, and it does not tell you which plan to buy. It explains what each type of cover is designed to do, and what you should actually read before you renew or sign.
Motor cover starts with other people, then adds your own car
In Malaysia, motor insurance is a legal requirement. The Persatuan Insurans Am Malaysia, in its guide to motor insurance types, sets out the usual ladder. Act cover is the statutory minimum for third-party injuries or deaths. Third party cover also includes damage to other people’s property. Third party, fire and theft adds fire damage or theft of your own vehicle. Comprehensive cover includes those third-party liabilities and also covers damage to your own car from accidents, fire and theft.
That is the same shape described on this overview of comprehensive motor cover: liability for other people’s death or injury and property, plus accidental or fire damage to your own car, and theft. Comprehensive is not the legal minimum. Third-party cover is. Flood, landslide and other natural disasters are commonly treated as special perils, which PIAM notes can be added to a comprehensive policy rather than being assumed. Agreed value and market value also produce different payouts if the car is written off, so the sum insured method belongs in the same review as the excess and any windscreen or named-driver add-ons.
Contractors’ all risks follows the building contract, not the calendar year
A motor policy renews around a registration date. A contractors’ all risks policy is built around a construction contract. On a contractors’ all risks product outline, the cover is described as protection against loss or damage to the contract works at the contract site, and against third-party claims arising in connection with the construction of a project. The duration is tied to the contract period set out in the letter of award, not to a standard one-year motor term.
Optional extensions may include construction plant and equipment, machinery, removal of debris, professional fees, and the principal’s existing property, usually for an additional premium. That matters if you are renovating a shop or building a small factory and assume your ordinary fire or motor policy will look after the works. It generally will not. Read the site description, the contract value, the period, and who is named as the insured, because a policy that starts too late or omits the principal can leave a hole right in the middle of the job.
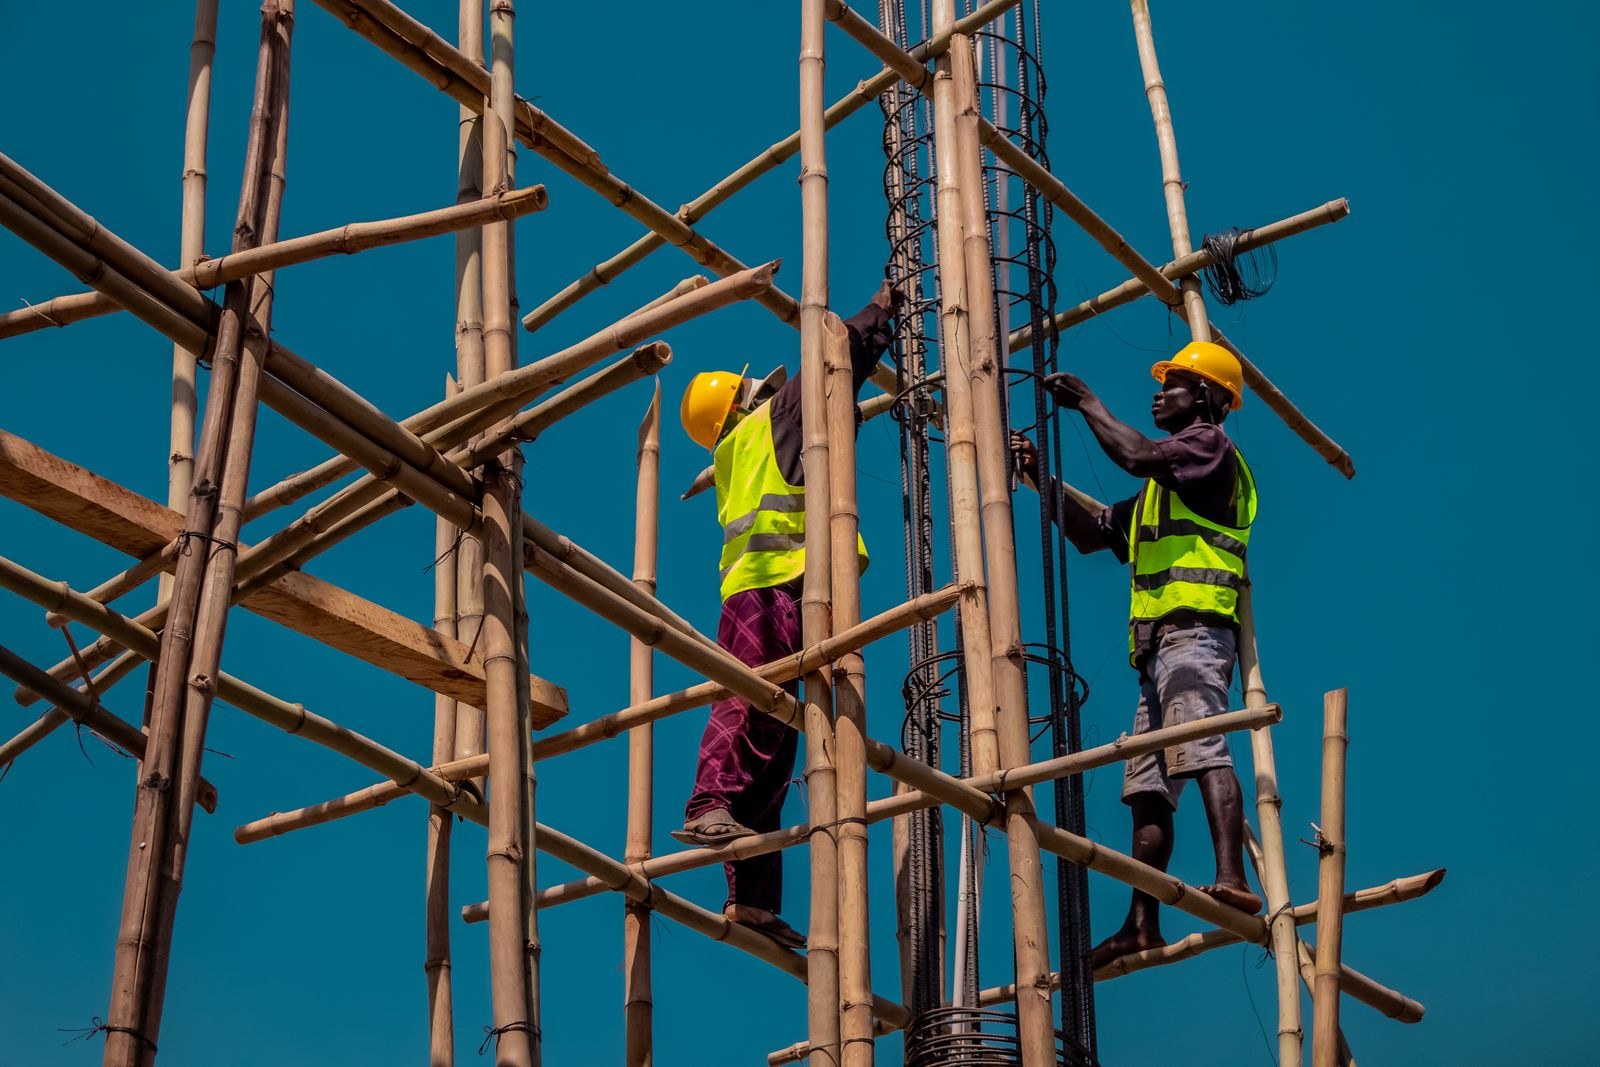
A works policy is tied to the contract on site. The start date, the site and who is named as the insured all need to match the job. Critical illness is a lump sum, not a course of treatment
Critical illness insurance is often sold in the same conversation as medical cover, which is how the two get blurred. They do different jobs. The Life Insurance Association of Malaysia, in its introductory guide to medical and health insurance, describes dread disease or critical illness insurance as a policy that pays a specified lump sum on diagnosis of any of 36 listed conditions or specified illnesses. Hospitalisation and surgical insurance, by contrast, is designed to help with the cost of private medical treatment.
The lump sum is not a treatment and it is not a cure. It does not replace oncology or cardiac care, and it does not promise that a condition will improve. It is money that can be used for income, travel, home adjustments or bills that a medical policy may not pay. Insurers may offer plans that list more conditions than the 36 mentioned in that industry primer, or that stage payments differently, so the only list that matters is the one in your policy and product disclosure sheet. Allianz’s critical illness plans page also notes that a survival period may apply before a benefit is paid, and that the period can vary by plan. Those conditions are set in the policy wording, not in a clinic leaflet. If a condition is not defined in the way your diagnosis is written, or if an exclusion applies, the lump sum will not be paid.
A lecture-style explainer of fixed-benefit health covers, the family of products that includes critical illness lump-sum plans.
What to read before you sign or renew
For motor cover, start with the product disclosure sheet and check whether special perils, windscreen and the sum insured method are what you think they are. For a building job, match the contractors’ all risks period to the letter of award and confirm who is insured. For critical illness, read the list of conditions, the definitions, the exclusions and any survival period, and keep it alongside your medical policy so you can see what each one does. Bank Negara Malaysia’s insurance and takaful section is the regulator’s home for the rules that licensed insurers and takaful operators work under, including product transparency and claims settlement. Buy only from a licensed insurer or its authorised agent, and keep the policy wording, not just the sales slide.